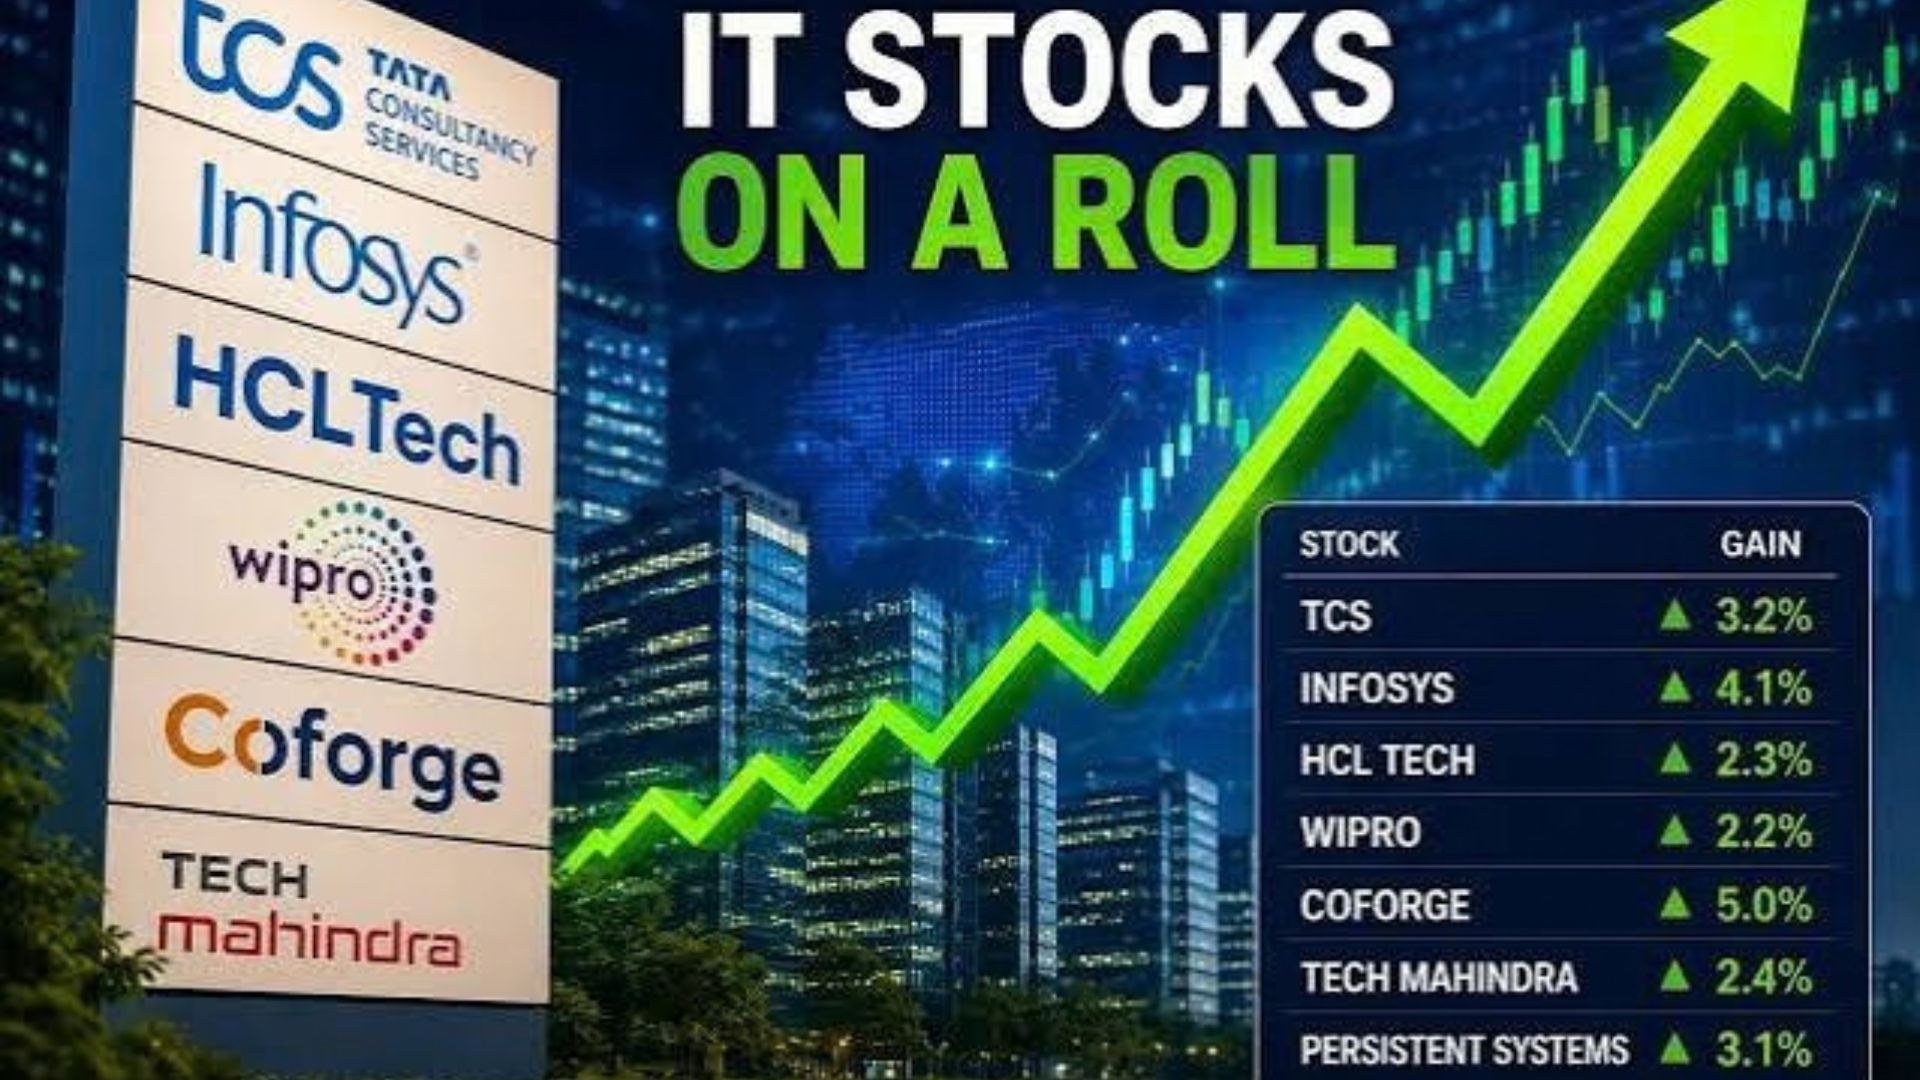
Indian IT stocks could see some improvement in Q2FY27, although analysts remain cautious about a broad-based recovery in technology spending. Weak discretionary demand, pricing pressure and global uncertainty continue to weigh on the sector.
Morgan Stanley has identified India’s IT services sector as a potential “dark horse” beneficiary of the artificial intelligence boom. It expects Indian technology companies to benefit as enterprises increasingly need implementation partners to deploy AI solutions. However, traditional IT services remain under pressure.
PL Capital expects a modest improvement in Q2FY27 and sees potential for select Tier-II companies to outperform larger peers as deal wins ramp up. It also expects the weaker rupee and moderation in wage costs to provide some margin support.
IDBI Capital expects large IT companies to report subdued growth of around 1%, citing weak volumes, pricing pressure and limited conversion of mega deals. It prefers TCS and HCLTech, while Kotak Institutional Equities sees Accenture’s strong performance as a positive read-through but says underlying demand remains limited.
Brokerage targets remain varied. PL Capital has a buy rating on TCS at ₹2,580, Infosys at ₹1,300 and Tech Mahindra at ₹1,900, while assigning a hold rating to HCLTech at ₹1,230 and Wipro at ₹154.
IDBI Capital has a buy rating on TCS with a ₹3,137 target and Tech Mahindra at ₹1,764. It has a hold rating on Infosys at ₹1,137, HCLTech at ₹1,380 and Wipro at ₹196.
YES Securities has buy ratings on TCS at ₹2,873, Infosys at ₹1,445, Wipro at ₹194 and Tech Mahindra at ₹1,960, while HCLTech carries a hold rating with a ₹1,367 target.
0 comments
No comments yet. Yours would be the first.