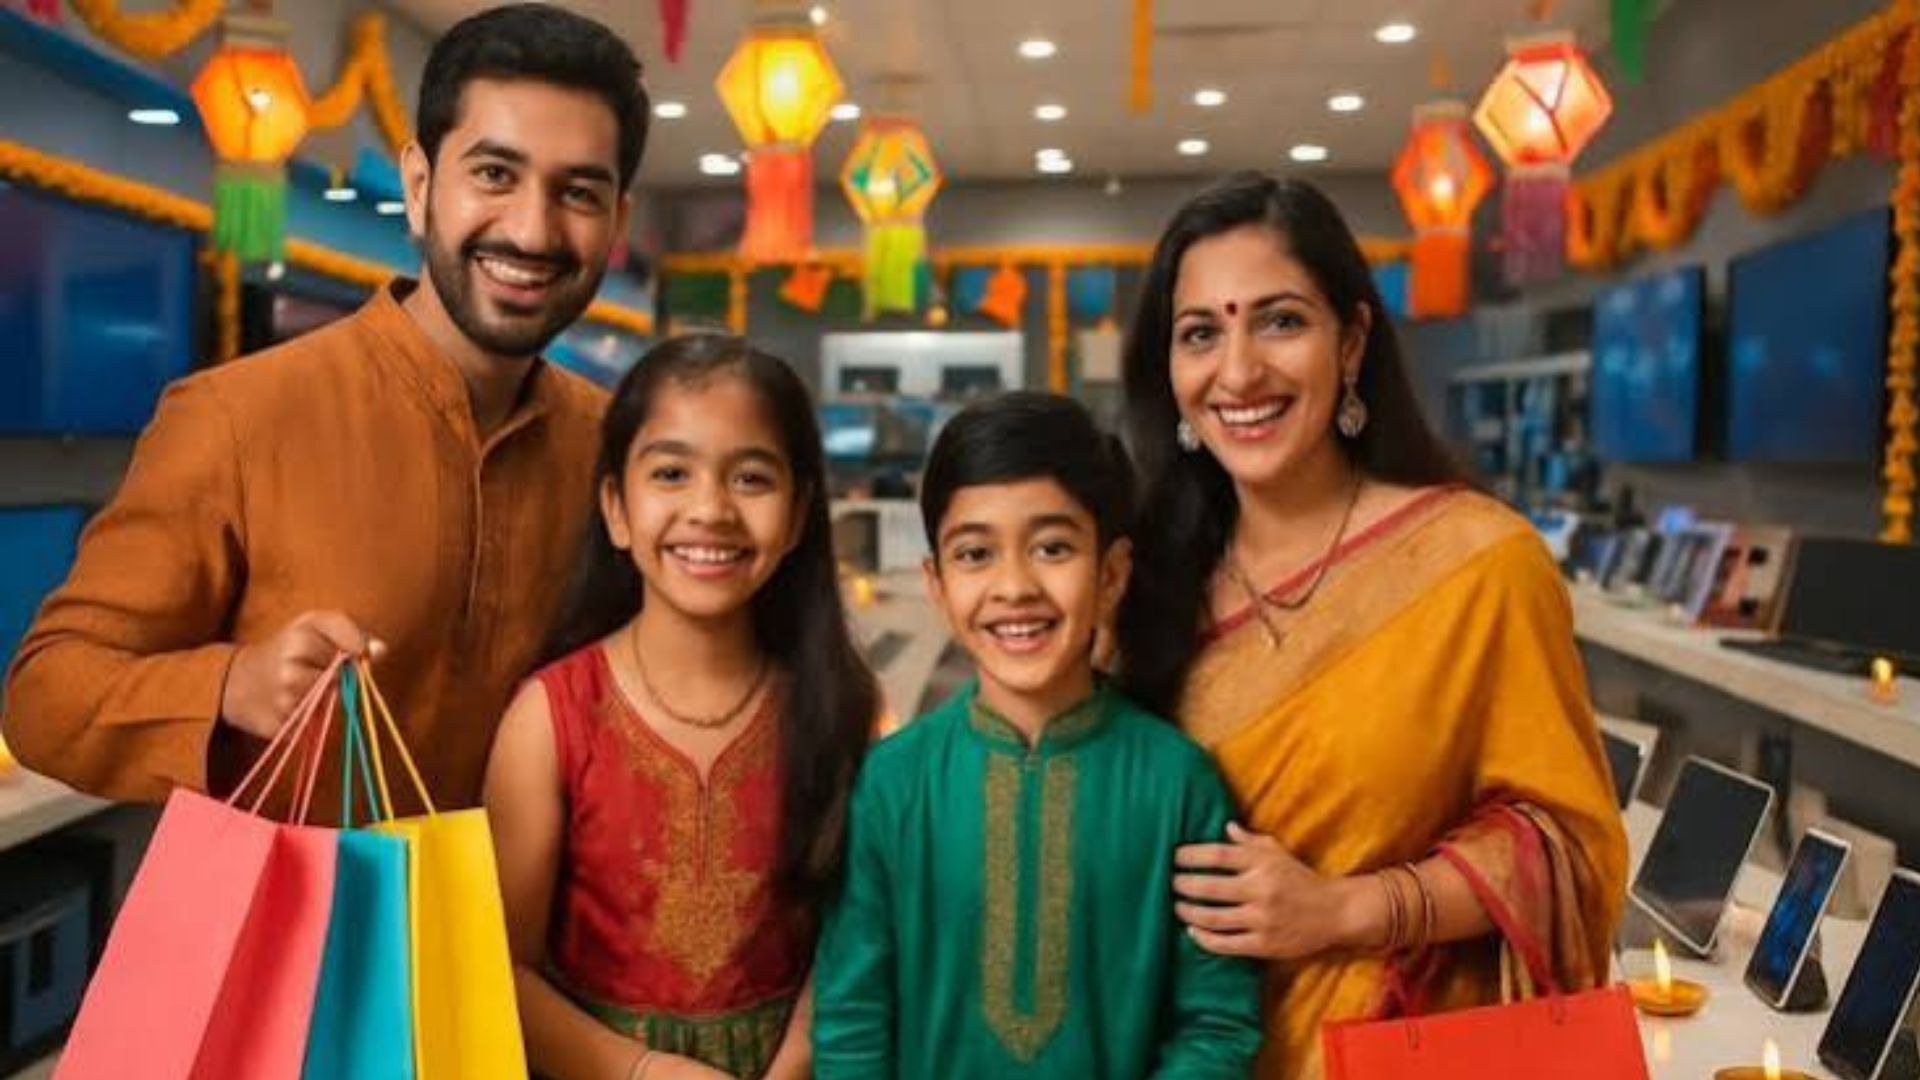
Festive discounts and easy EMI options can make expensive purchases seem affordable, but multiple monthly instalments can put pressure on household finances. A survey by Finnovate Financial Services found that 56% of 941 respondents used debt to maintain their standard of living, while one in 13 described their debt as unmanageable.
For a household earning ₹1 lakh a month, existing EMIs of ₹25,000 could rise to ₹40,000 after adding a new ₹15,000 instalment. That would mean 40% of monthly income going towards loan repayments, leaving less room for unexpected expenses, savings and investments.
Before buying, follow three simple rules. First, set a festive budget after accounting for essential expenses, existing loans and regular investments. Second, compare the total cost of an EMI offer, including interest, processing fees and repayment tenure, rather than focusing only on the monthly instalment. Third, protect your emergency fund, ideally covering three to six months of essential expenses.
Avoid stopping a systematic investment plan (SIP) simply to fund discretionary shopping. Regular investments can support long-term wealth creation, although contributions may need to be reviewed if essential expenses and loan repayments become difficult to manage.
The key is to buy within your means. A festive purchase should not create financial stress long after the celebrations end.
0 comments
No comments yet. Yours would be the first.