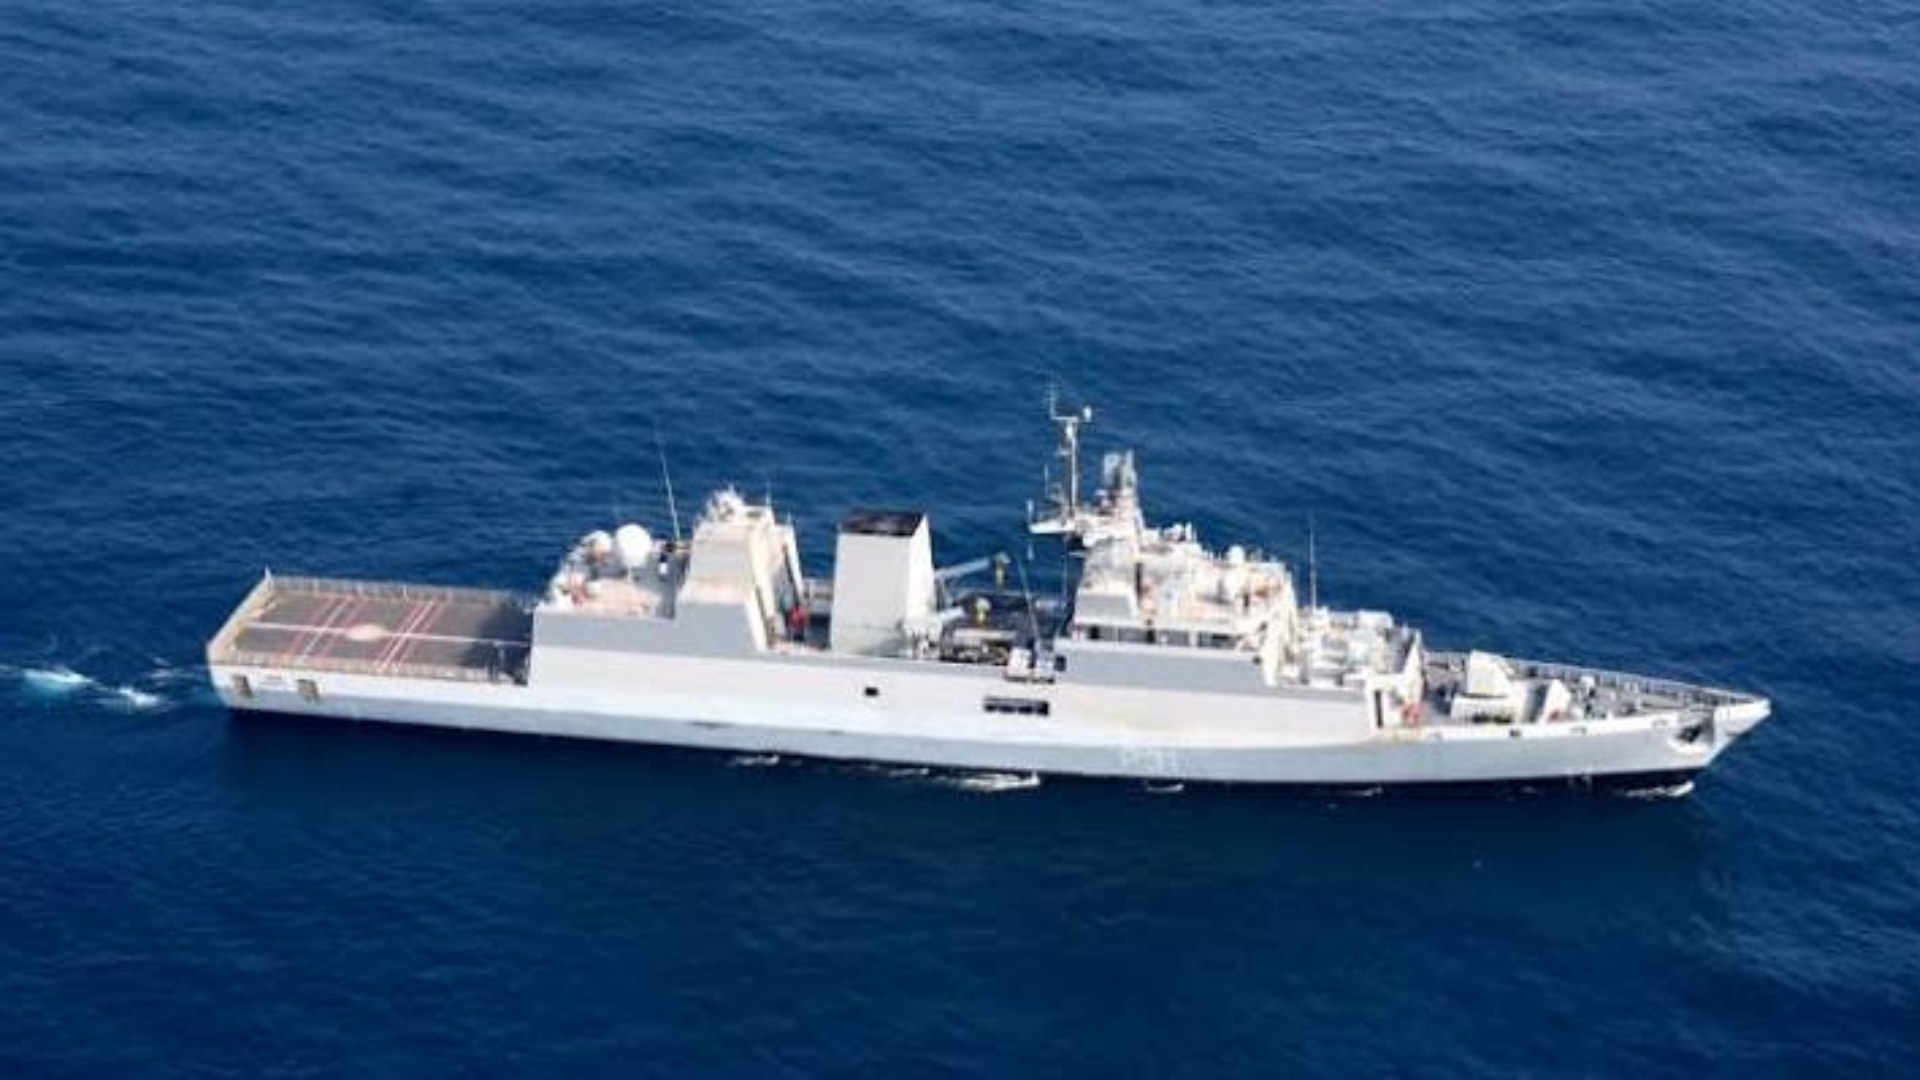
Garden Reach Shipbuilders & Engineers (GRSE) remains under scrutiny from brokerages following delays in the execution timeline of its Next Generation Corvette (NGC) programme, with Elara Capital retaining its Reduce rating on the stock.
Elara expects meaningful revenue contribution from the five-warship programme to begin only from FY29. The brokerage highlighted that the contract's delayed signing has pushed back revenue recognition and affected its earnings estimates.
GRSE signed the ₹32,000-crore contract with the Indian Navy on November 2 for the construction of five Next Generation Corvettes. The programme is scheduled to be completed within nine years and four months from receipt of the first-stage payment.
The pre-production phase, involving design and procurement, is expected to contribute a relatively small portion of project revenue, with execution expected to accelerate from FY29.
Elara reportedly cut its earnings per share estimates by 10% for FY27, 1% for FY28 and 7% for FY29. It lowered its target price to ₹2,050 from ₹2,230 while retaining its Reduce rating.
The brokerage expects GRSE's near-term growth to be influenced by execution of existing orders, smaller shipbuilding projects and spares, while the new corvette programme gradually ramps up.
Choice Institutional Equities, however, remains positive on the company. It retained its Buy rating and target price of ₹3,500, citing the strong order book, expanding defence pipeline and execution opportunities. The brokerage expects revenue, EBITDA and profit growth over FY26-FY29.
The differing brokerage views reflect the contrast between GRSE's long-term order visibility and the timing of revenue and earnings conversion.
0 comments
No comments yet. Yours would be the first.